
On this page
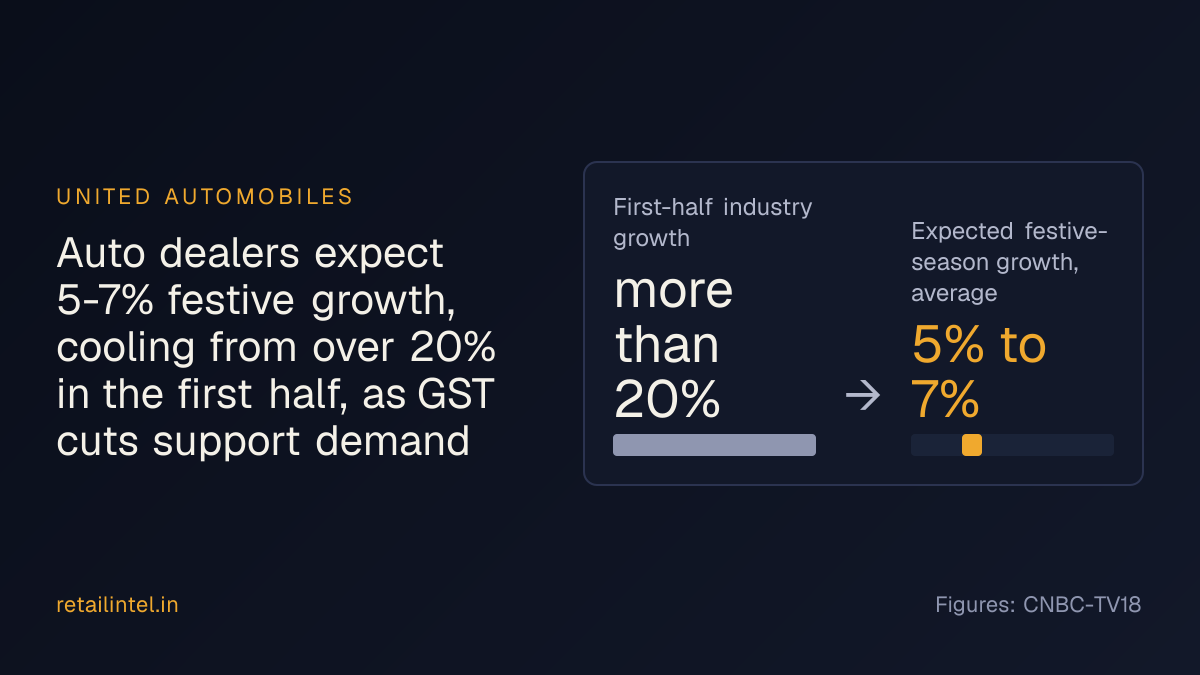
Auto dealers expect 5-7% festive growth, cooling from over 20% in the first half, as GST cuts support demand
Our read
Festive growth most likely settles in the 5-7% range, well below the first half's over 20%, and the unusually high North India stock keeps discounting and dispatch curbs in play.
For operators
Plan festive sales around 5-7% growth rather than the over 20% of the first half, and prioritise clearing North India stock of around 45 days (normal is 21-25) while GST-cut-aided demand lasts.
Watch
October and November retail registrations against the 7-8% passenger-vehicle and about 10% two-wheeler expectations
The report
United Automobiles' Vinkesh Gulati expects passenger vehicles to grow 7-8% in October-November and two-wheelers around 10%, helped by GST cuts. Akshaya Motors' Shyam sees growth of 12-15%, while a 25-basis-point rate hike could pressure entry-level buyers.
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| North India inventory: | around 45 days |
|---|
What to watch next
- North India dealer stock days falling from around 45 toward the 21-25 norm
- Makers' wholesale dispatches running below retail sales
- Wider or extended discount schemes in the festive weeks
- Dealer-body commentary after Diwali on whether festive growth finished inside 5-7%
The counter-case
The case against this reading — not reported by the source.
The headline number does not match the evidence beneath it. The 5-7% festive average sits below every segment figure cited: passenger vehicles up 7-8%, two-wheelers about 10%, and Akshaya Motors at 12-15%. Either weaker segments are dragging the average down without being named, or the figures come from different dealers, periods and baselines, so the 'cooling' story may be partly an artefact of mixing them. All of it is dealer sentiment, not registrations or retail data. Dealers have reasons to talk up GST-led demand, and the forecasts are unaudited. The inventory figure is the sharpest warning: North India stock of about 45 days against a normal 21-25 is nearly double. That points to supply pushed into the channel ahead of demand, which means heavy discounting, squeezed dealer margins and possible financing stress if the festive season underdelivers. If GST cuts pulled purchases forward, October-November could fall short of even 5-7%. Comparing festive growth with first-half growth also mixes seasons and bases, so 'down from over 20%' may overstate the slowdown or misread its cause.
The source
First seen