
On this page
Our read
Indian FMCG sector will likely see margins stay squeezed until at least the March 2027 quarter.
For operators
Systematix expects 10 staples firms to grow revenue about 13% on an 8% volume rise and 5%-6% price increases, so retailers should expect continued shelf price rises and steady demand while supplier margins stay squeezed.
Watch
Operating-margin decline past Systematix's 45 bps at the September-quarter results would mean Kotak's 150 bps view is nearer and the price rises are not covering costs.
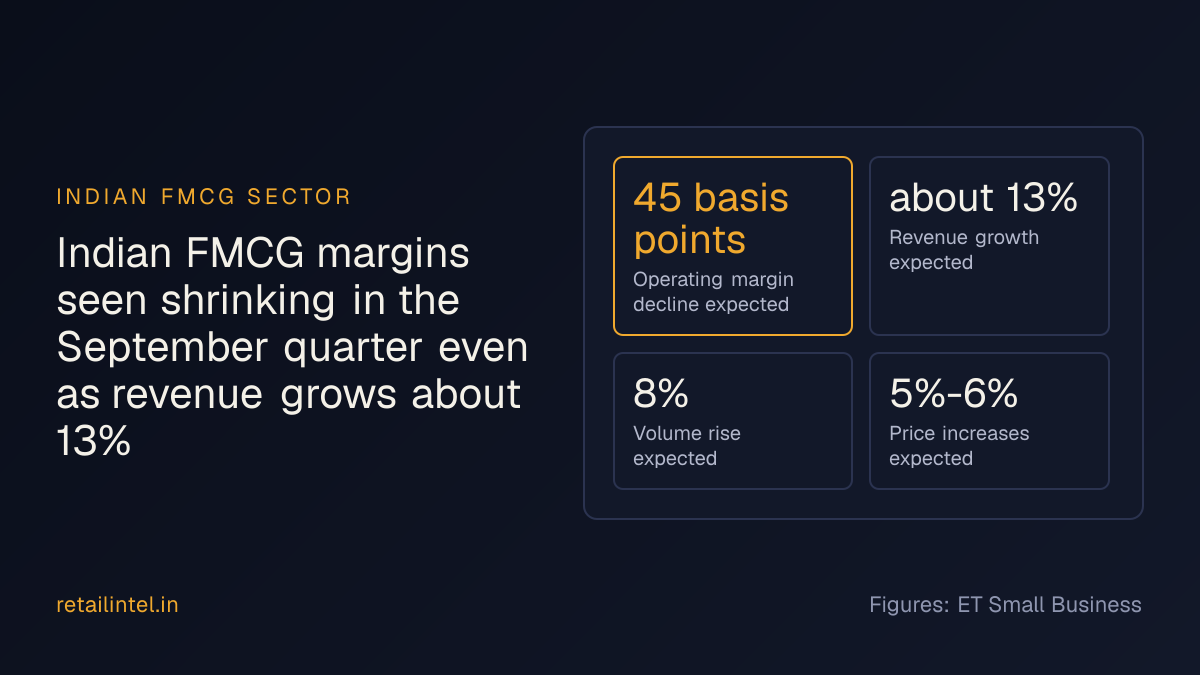
The report: Indian FMCG margins seen shrinking in the September quarter even as revenue grows about 13%
Systematix expects operating margins at 10 major consumer staples firms to shrink 45 basis points in the September quarter despite revenue growth of about 13%. Kotak forecasts a steeper 150-basis-point decline, with Hindustan Unilever and Britannia hit hardest.
- Operating margin decline expected
- 45 basis points
- Revenue growth expected
- about 13%
- Volume rise expected
- 8%
- Price increases expected
- 5%-6%
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| Systematix expected volume rise: | 8% |
|---|---|
| Systematix expected price increases: | 5%-6% |
| Britannia expected margin drop (Systematix): | 137 basis points |
Why it matters to operators and investors
With margins at 10 staples firms forecast to fall 45 basis points (Systematix) to 150 basis points (Kotak) and no recovery before the March 2027 quarter, FMCG targets may be open to portfolio pruning or valuation resets.
What to watch next
- Volume growth versus the 8% estimated for the quarter
- Realised price increases against the 5%-6% assumed
- Management guidance on margin recovery from the March 2027 quarter
- Commentary on input costs and trade-channel schemes in results calls
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- Large staples companies are likely to defend margins by holding the 5%-6% price increases rather than rolling them back.
- Expect managements to frame the September-quarter margin dip as temporary and point to recovery from the March 2027 quarter.
- Brokerages such as Kotak and Systematix may revise estimates once actual results show whether the fall is nearer 45 bps or 150 bps.
- Rivals and regional players may use sharper pricing or promotions to chase share if volume growth slows from the 8% pace.
- Distributors and retailers are likely to push for higher trade margins or schemes if brands keep raising prices.
The counter-case
The case against this reading — not reported by the source.
The -45 bps figure is a single broker's forecast for 10 companies, not reported results, and it may not be the right anchor. Kotak's 150 bps drop is more than three times larger, so the brokers disagree on the size of the squeeze. The 13% revenue growth rests on two assumptions that could fail: 8% volume growth and 5%-6% price increases. If price rises meet consumer resistance, volumes could slow and the margin hit could be nearer Kotak's number or worse. If input costs ease or pricing sticks, margins could come in better than Systematix expects, which would make the 'shrinking margins' headline look too bearish. The recovery date of March 2027 'at the earliest' is a soft call that analysts often revise. A basket-level average also hides large differences between companies. A few large names can swing the aggregate, so the headline may not describe a typical staples firm.
The source
Filed
First seen