On this page
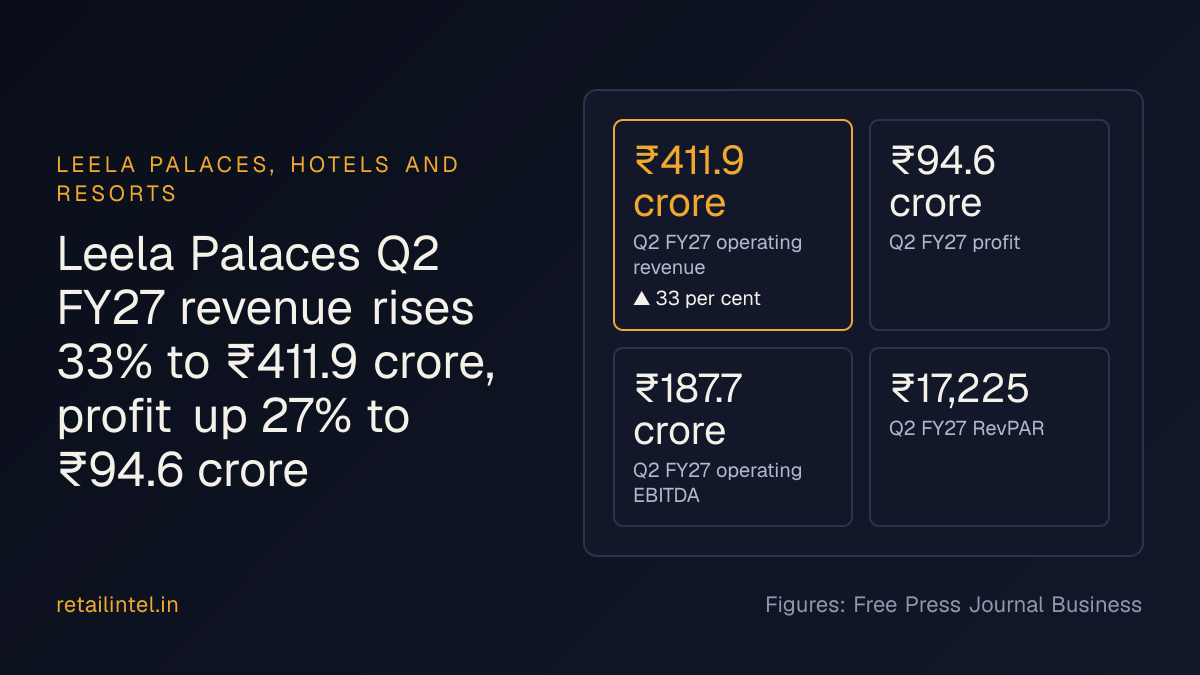
Leela Palaces Q2 FY27 revenue rises 33% to ₹411.9 crore, profit up 27% to ₹94.6 crore
Our read
Leela's Q2 growth rests on pricing power, and it will more likely than not carry into the FY27 openings if ADR holds near ₹25,046 and net debt stays near ₹1,215 crore.
For operators
Leela Palaces' RevPAR rose 30% to ₹17,225 and ADR reached ₹25,046, which shows affluent consumers are still paying premium rates, so retail and F&B operators in luxury-heavy locations can expect strong high-end spending to continue.
Watch
Announcement of the first pipeline hotel opening before the end of FY27
The report,
Leela Palaces Hotels & Resorts saw revenue per available room (RevPAR) rise 30 per cent year-on-year to ₹17,225 in the quarter ended 30 September 2026. Its pipeline stands at 1,038 keys across 10 properties.
- Q2 FY27 operating revenue
- ₹411.9 crore
- up 33 per cent
- Q2 FY27 profit
- ₹94.6 crore
- Q2 FY27 operating EBITDA
- ₹187.7 crore
- Q2 FY27 RevPAR
- ₹17,225
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| Q2 FY27 operating EBITDA: | ₹187.7 crore |
|---|---|
| Q2 FY27 ADR: | ₹25,046 |
| Net debt as of September 30, 2026: | ₹1,215 crore |
Why it matters to operators and investors
Leela Palaces' pipeline of 1,038 keys across 10 properties, with openings expected in FY27, points to organic expansion, so any partnership or deal angle is limited to new-property tie-ups while net debt stands at ₹1,215 crore.
What to watch next
- RevPAR above Q2's ₹17,225 in the Q3 FY27 results would mean rate-led growth is holding into peak season, leaving rivals less room to win share by discounting.
- ADR in the Q3 FY27 results against Q2's ₹25,046
- Net debt at the next reporting date against ₹1,215 crore as of 30 September 2026
- Operating EBITDA in the next results against Q2's ₹187.7 crore
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- Leela Palaces Hotels & Resorts is likely to open or formally date the first of its pipeline hotels within FY27, moving part of the 1,038 keys across 10 properties into operation.
- Expect Leela Palaces Hotels & Resorts to keep leaning on pricing, aiming to hold ADR near ₹25,046 rather than chase occupancy with discounts.
- Lenders may stay comfortable with net debt of ₹1,215 crore while operating EBITDA of ₹187.7 crore keeps growing, which could ease terms on pipeline funding.
- Rival luxury hotel chains may respond to Leela's rate gains by raising their own premium rates and bringing forward flagship launches in the same destinations.
- Expect Leela Palaces Hotels & Resorts to stress the pipeline and rate-led RevPAR growth in investor commentary, as the 30% RevPAR rise is the main evidence for its premium positioning.