
On this page
Our read
Paytm will more likely than not see a narrow UPI MDR from NPCI after Diwali, keeping Nomura's case intact.
For operators
NPCI has deferred its proposed UPI MDR (0.4% on person-to-merchant payments above Rs 2,000, capped at Rs 300 from Rs 75,000) until after Diwali, so retailers should model checkout costs on large-ticket baskets but need not reprice yet.
Watch
NPCI's final UPI MDR above the proposed 0.4% on P2M over ₹2,000, when issued after Diwali, would mean Paytm's payments margin upside is thinner than Nomura models.
The report: Nomura initiates Paytm at Buy with Rs 2,250 target as NPCI defers UPI MDR framework until after Diwali
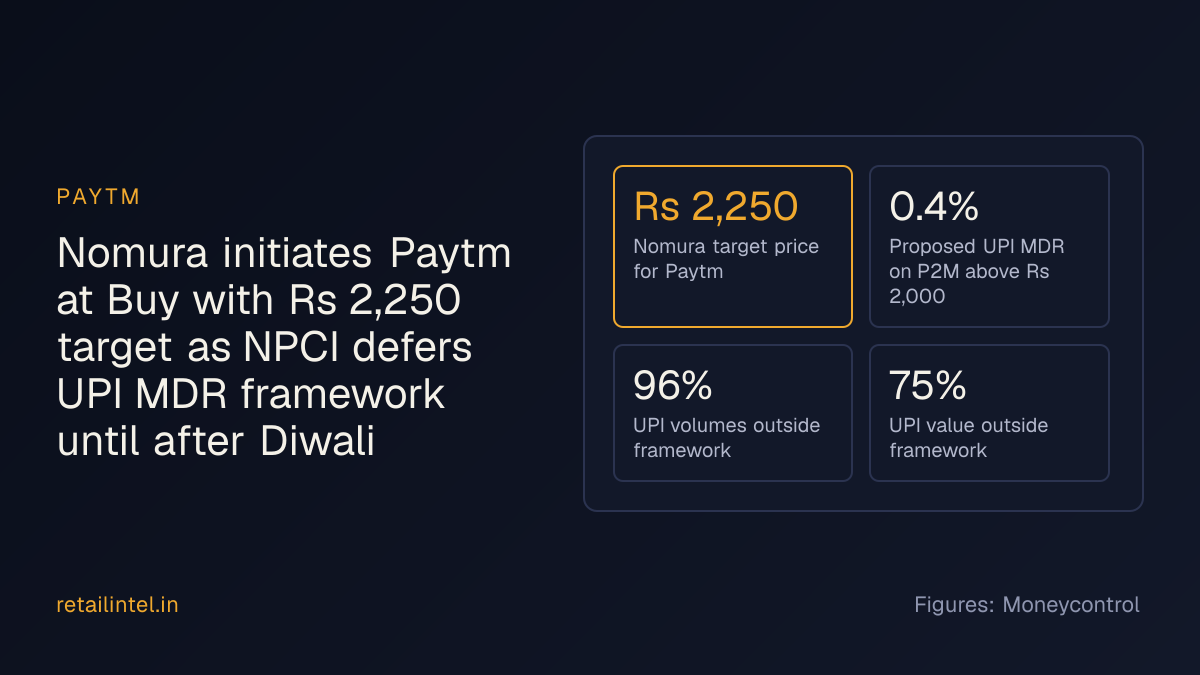
NPCI deferred its proposed UPI MDR framework, which sets a 0.4% charge on person-to-merchant transactions above Rs 2,000, until after Diwali. Nomura initiated Paytm at Buy with a Rs 2,250 target, expecting a 96% EBITDA CAGR between FY26 and FY29.
- Nomura target price for Paytm
- Rs 2,250
- Proposed UPI MDR on P2M above Rs 2,000
- 0.4%
- UPI volumes outside framework
- 96%
- UPI value outside framework
- 75%
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| MDR cap for transactions of Rs 75,000 or more: | Rs 300 |
|---|---|
| Flat charge for railways, telecom, fuel, insurance: | Rs 5 |
| Capital markets transactions MDR: | 0.02% |
| UPI value outside charging framework: | 75% |
Why it matters to operators and investors
Nomura's Rs 2,250 Paytm target and an MDR framework that leaves 96% of UPI volumes outside it give payments assets a pricing reference, so acquirers and partners should wait for the post-Diwali rules before benchmarking merchant economics.
What to watch next
- Paytm's Q2 FY27 EBITDA against Nomura's 96% FY26-FY29 CAGR path
- Share of UPI value outside the framework moving away from the stated 75%
- Any NPCI notice pushing the MDR decision past the post-Diwali timing
- Paytm share price against Nomura's ₹2,250 target after the MDR clarity
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- NPCI is likely to publish a final UPI MDR framework only after Diwali, keeping the flat ₹5 band for railways, telecom, fuel and insurance.
- Paytm is likely to keep stressing merchant-side products and operating leverage on its next results call, rather than leaning on an MDR windfall.
- Rival payment apps and merchant bodies may lobby NPCI to cut the 0.4% rate or raise the ₹2,000 threshold before the rules are final.
- Other brokerages may revisit their Paytm ratings and EBITDA estimates once the MDR rules are clear, with Nomura's 96% FY26-FY29 EBITDA CAGR as the bull-case marker.
- Large billers in the flat-rate sectors are likely to press for exemptions or a lower fee, since they carry the most volume.