
On this page
Our read
Orient Electric is likely to keep widening margins into H2 FY27 as BLDC fans lift its mix.
For operators
Orient Electric's Q2 FY27 revenue rose 25.2% to ₹879.3 crore and its BLDC fan portfolio grew 26%, so electricals retailers should treat BLDC fans as a growing range when planning shelf and stock.
Watch
BLDC fan growth versus the 26% reported for Q2
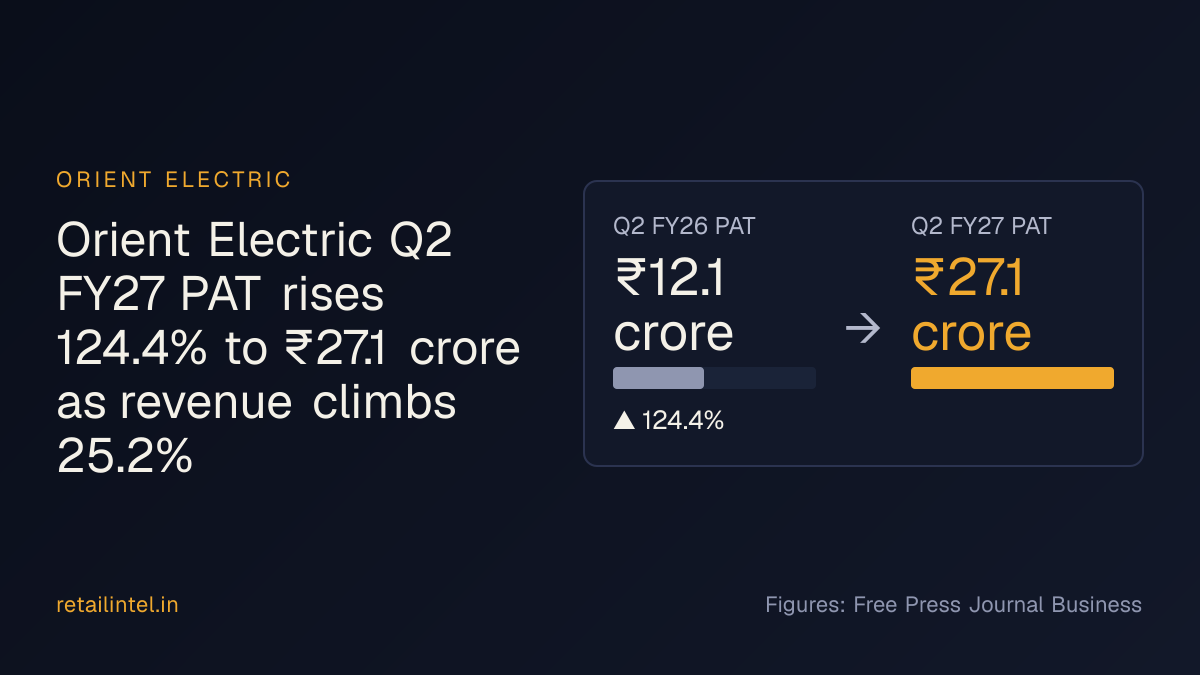
The report, : Orient Electric Q2 FY27 PAT rises 124.4% to ₹27.1 crore as revenue climbs 25.2%
Orient Electric's profit after tax was up from ₹12.1 crore a year earlier, on Q2 FY27 revenue of ₹879.3 crore. EBITDA rose 49.7% to ₹56.8 crore, and the BLDC fan portfolio grew 26%.
up 124.4%
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| Q2 FY27 EBITDA margin: | 6.5% |
|---|---|
| H1 FY27 revenue: | ₹1,829.1 crore |
Why it matters to operators and investors
Orient Electric posted 49.7% EBITDA growth to ₹56.8 crore and 26% BLDC fan growth, which makes it a stronger consumer-electricals benchmark, though the 6.5% margin limits how much value the earnings recovery supports.
What to watch next
- EBITDA margin above Q2's 6.5% in the Q3 FY27 results would mean operating leverage is holding and rivals' discounting is not eroding Orient's gains.
- Revenue growth versus the 25.2% reported for Q2, in the Q3 FY27 results
- Rival fan makers' pricing and promotion commentary in their next results
- Management commentary on input costs and dealer inventory in the next results
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- Orient Electric is likely to keep pushing BLDC fans and premium products, since that portfolio grew 26% and carries better mix than basic fans.
- Expect Orient Electric's management to point to operating leverage and cost discipline as the reason EBITDA grew 49.7%, and to guide for margins to be sustained rather than expanded sharply.
- Rival fan and appliance makers such as Havells and Crompton may respond to Orient's growth with sharper BLDC pricing, dealer schemes and new launches.
- Distributors and dealers are likely to widen Orient's BLDC and premium shelf space if sell-out matches the Q2 sell-in, and to pull back quickly if it does not.
- Analysts are likely to lift FY27 estimates for Orient Electric but ask whether H1 FY27 revenue of ₹1,829.1 crore can be sustained in the second half.
The source
Published
First seen