
On this page
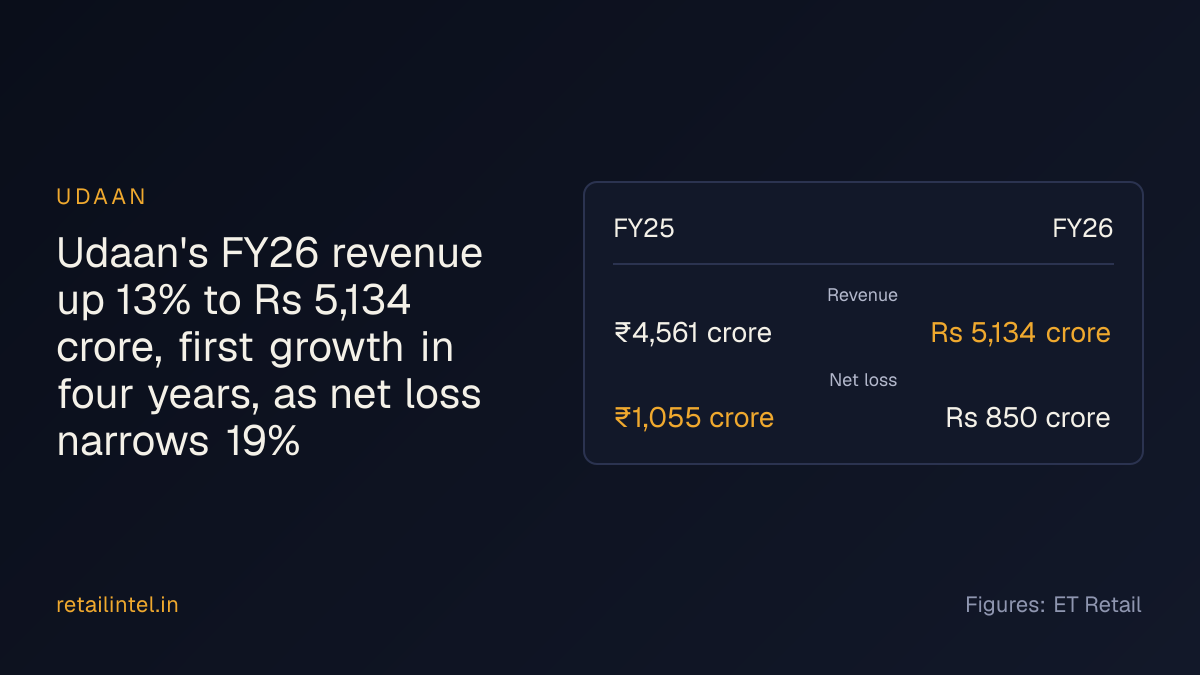
Udaan's FY26 revenue up 13% to Rs 5,134 crore, first growth in four years, as net loss narrows 19%
Our read
Udaan grew FY26 operating revenue 13% to Rs 5,134 crore after a 20% fall in FY25, so retailers and wholesalers competing for kirana supply should expect a tighter cluster-led rival pushing private labels in staples.
Watch
Private-label share of staples sales against the current 15-25% range
The report
Udaan cut its FY26 net loss to Rs 850 crore after moving to a cluster-led operating model that makes city and category teams accountable for performance. It is also growing private labels, now approximately 15-25% of staples sales across operating cities.
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| FY25 revenue decline: | 20% |
|---|---|
| July recapitalisation: | $160-million |
| Lynk Logistics deal valuation: | Rs 500 crore |
Why it matters to operators and investors
With a $160-million recapitalisation in July, a cluster-led model and private labels at 15-25% of staples sales, Udaan looks like a stabilising but still loss-making B2B platform, so partnership or deal talks would be on its terms.
What to watch next
- FY27 revenue growth above the 13% reported for FY26, at the FY27 results, would mean the rebound outlasts the low FY25 base and rivals face a durable Udaan.
- Net loss trend against the ₹850 crore reported for FY26
- Any fresh funding round after the $160-million July recapitalisation
- Rival B2B platforms' changes to retailer credit terms or pricing
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- Udaan is likely to extend the cluster-led model to more demand-dense areas, before it adds geographies where order density is thin.
- Expect Udaan to push private labels beyond the current 15-25% of staples sales, since own-brand lines give it more control over margin and supply.
- Udaan's recapitalisation investors are likely to tie further support to a visible, continued narrowing of losses rather than to growth alone.
- Rival B2B platforms and retailers' wholesale arms may answer a recovering Udaan with sharper pricing and credit terms for small retailers.
- Staples suppliers are likely to renegotiate terms with Udaan as its own-brand share rises, with bigger brands pushing for shelf and volume commitments.
The source
First seen