On this page
Resurfaced July 12 brokerage view: Indian retailers' Q1 FY27 seen strong; V2 Retail +58%, V-Mart +23%, Trent +19%
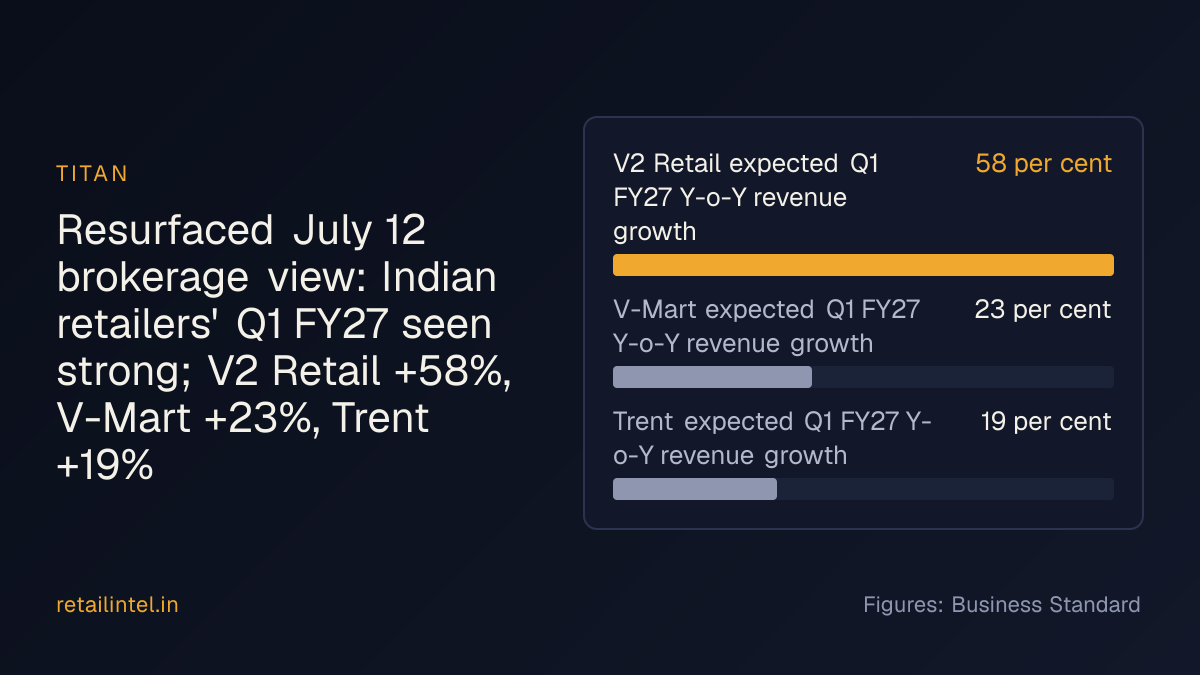
Brokerages expect strong Q1FY27 retail results; Systematix cites year-on-year revenue growth of 23 per cent at V-Mart, 58 per cent at V2 Retail and 19 per cent at Trent. Jewellers are seen buoyant, while Bata stays sluggish.
- V2 Retail expected Q1 FY27 Y-o-Y revenue growth58 per cent
- V-Mart expected Q1 FY27 Y-o-Y revenue growth23 per cent
- Trent expected Q1 FY27 Y-o-Y revenue growth19 per cent
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| Metro Brands expected toppling growth: | 15 per cent |
|---|---|
| Metro Brands expected Ebidta margin contraction: | 30 basis points |
| Gold price correction from peak: | around 20 per cent |
| Adhik Maas period: | May 17 to June 15 |
Why it matters to operators and investors
Brokerages expect value-fashion chains like V2 Retail (+58%), V-Mart (+23%) and Trent (+19%) to grow on demand and new stores, so measure your Q1 against that pace, and note that Metro's roughly 30bps EBITDA margin dip despite about 15% growth shows expansion can cost margin while Bata stays sluggish.
What to watch next
- V2 Retail's reported April–June revenue growth versus the 58% estimate
- V-Mart and Trent growth prints versus 23% and 19%
- Metro Brands' EBITDA margin change versus the ~30bps contraction expected
- Gold price moving back toward its peak from about 20% below
- Bata's growth commentary and whether demand stays sluggish
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- V2 Retail is likely to report growth close to the 58% estimate and point to continued store expansion as the driver.
- Trent is likely to keep its store-growth-led momentum, with revenue growth around the ~19% brokerages expect.
- Metro Brands may report roughly 15% topline growth alongside modest EBITDA margin contraction, and its commentary will probably stress cost pressure.
- Bata is likely to stay the laggard of the group, with sluggish demand reflected in muted growth relative to peers.
- Jewellers are likely to post strong quarters as gold trading about 20% below its peak supports buying, and brokerages may lift estimates after results.
The source
Published
First seen