
On this page
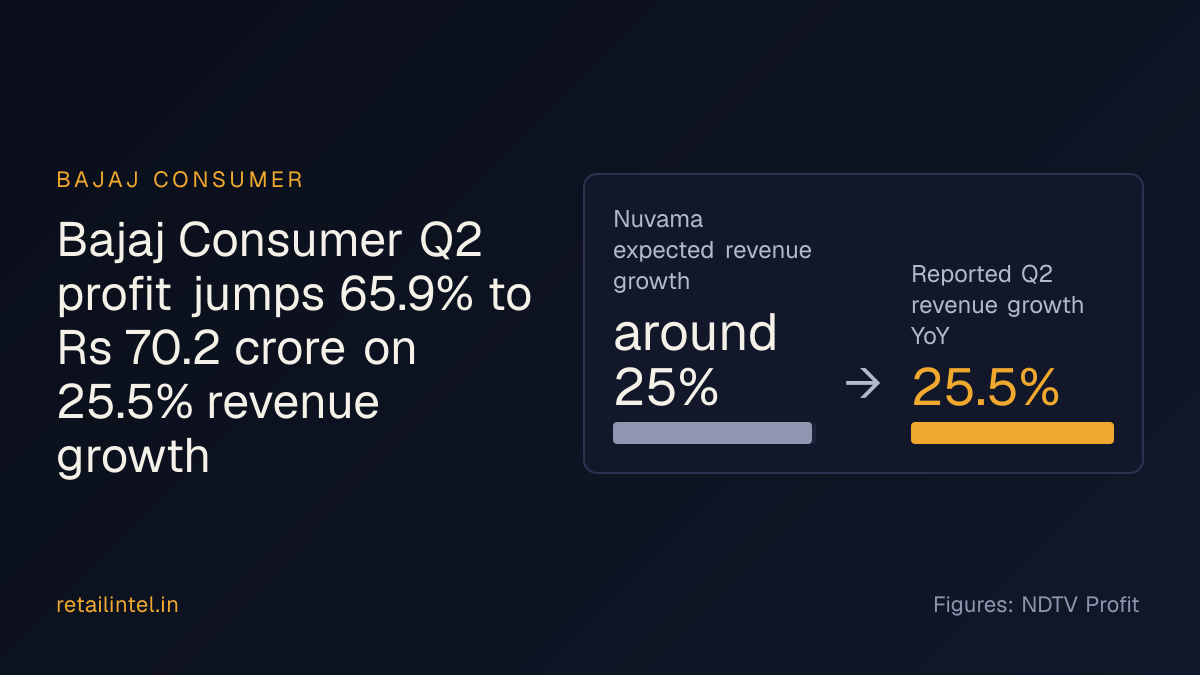
Bajaj Consumer Q2 profit jumps 65.9% to Rs 70.2 crore on 25.5% revenue growth
Our read
Bajaj Consumer will more likely than not keep its margin near the Q2 level while revenue growth eases from 25.5%.
For operators
Bajaj Consumer's Q2 net profit rose 65.9% to Rs 70.2 crore on 25.5% revenue growth to Rs 333 crore, so retail operators can read it as a sign of healthy FMCG demand, though the brand's own results are not a read on any one retailer's sell-through.
Watch
Rival FMCG makers' commentary on hair-oil volumes and pricing in their next results
Ask next
How do Bajaj Consumer's results compare with its rivals?The report
Bajaj Consumer posted revenue of Rs 333 crore and an EBITDA margin of 24.7%. Jio Platforms set its IPO price band at Rs 1,065-1,119 per share, opening 21 October. Bluestone Jewellery's board meets 22 October on raising Rs 300 crore via NCDs.
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
What to watch next
- EBITDA margin above Q2's 24.7% at the Q3 results would mean the profit jump is structural, leaving rivals less room to win share with promotions.
- Q3 revenue growth against the 25.5% reported for Q2
- Jio Platforms IPO subscription levels after the 21 October opening
- Bajaj Consumer share price and broker target changes after the results
The counter-case
The case against this reading — not reported by the source.
The 65.9% profit jump is a headline number off what looks like a small, possibly depressed base, so it may overstate how strong the business is. Net profit of Rs 70.2 crore on revenue of Rs 333 crore is a net margin of about 21%, close to the 24.7% EBITDA margin. That leaves very little room for depreciation, interest and tax. It points to a large contribution from other income (treasury income on surplus cash), a low tax charge or a one-off item, rather than operating strength. Profit growth of 65.9% against revenue growth of 25.5% also suggests the gain came mainly from margin expansion, probably cheaper inputs, and not from sustainable volume growth. If input costs reverse or promotional spend rises, the margin gain could fade quickly. Bajaj Consumer is a small-cap hair-oil company, so one quarter of 25.5% growth says little about a durable trend. The deck also adds the Jio Platforms IPO and Bluestone's NCD board meeting, which are unrelated to this result. They inflate the item's apparent significance, and the 'retail-company' tag is a stretch for a manufacturer.
The source
First seen