
On this page
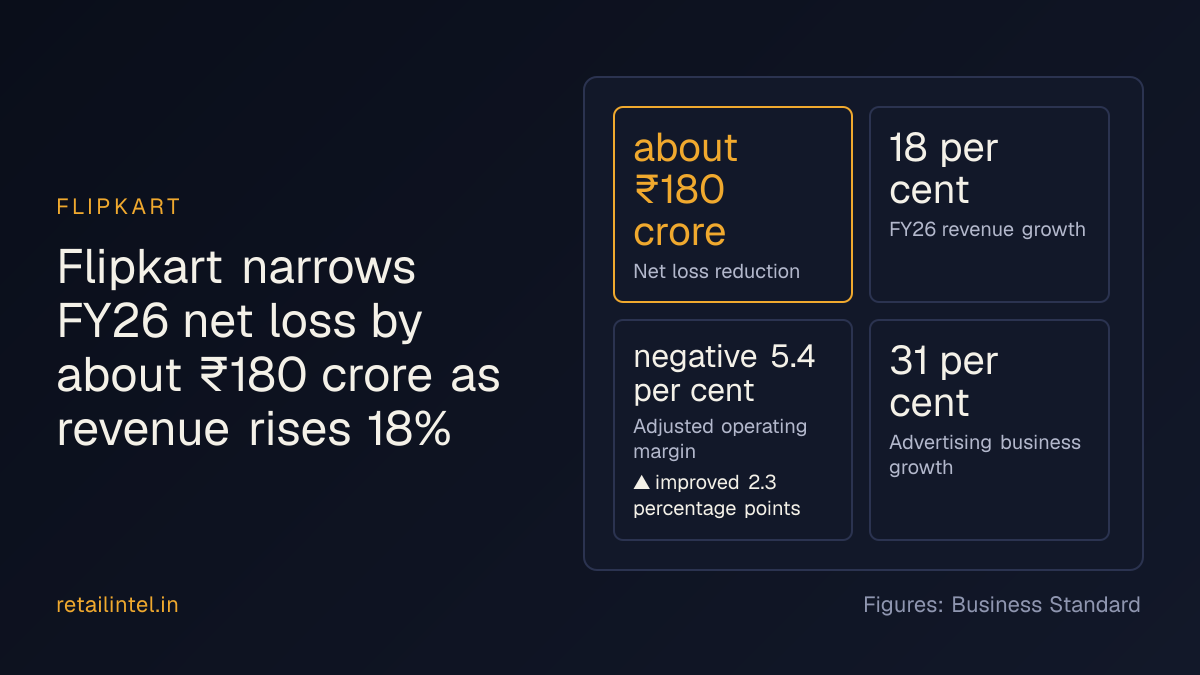
Flipkart narrows FY26 net loss by about ₹180 crore as revenue rises 18%
Our read
Flipkart grew FY26 revenue 18% and lifted adjusted operating margin 2.3 points to negative 5.4% with advertising up 31%, so rival e-commerce and quick-commerce operators face a competitor getting more efficient and monetising through ads.
Watch
Advertising growth against FY26's 31% in the next disclosure
The report,
Flipkart's adjusted operating margin improved 2.3 percentage points to negative 5.4 per cent, and its advertising business grew 31 per cent. Higher finance costs, deferred tax asset derecognition and one-off items limited the reduction in net loss, RoC filings show.
- Net loss reduction
- about ₹180 crore
- FY26 revenue growth
- 18 per cent
- Adjusted operating margin
- negative 5.4 per cent
- up improved 2.3 percentage points
- Advertising business growth
- 31 per cent
One email each morning: the day’s top moves in Indian retail, why each matters and what to watch. Free. Stop any time.
Reported figures
From the report. Source details below
| Adjusted Ebitda improvement: | roughly ₹1,500 crore |
|---|---|
| Gross margin increase: | 23 per cent |
| Adjusted operating loss narrowing: | approximately ₹1,600 crore |
Why it matters to operators and investors
Flipkart's FY26 loss narrowed by about ₹180 crore on 18% revenue growth and 31% advertising growth, so any partnership or valuation view should treat it as a still loss-making group whose economics are improving.
What to watch next
- Adjusted operating margin above negative 5.4% in the FY27 filings would mean loss narrowing is durable, easing pressure on investors and sellers.
- Parent-company commentary on Flipkart losses in its next quarterly results
- Any fundraising or listing-related filing by the Flipkart group
- Pricing or delivery-speed moves by Amazon India and Reliance Retail
Likely next moves
Our read of what comes next — analysis, not reported by the source.
- Flipkart is likely to lean harder on advertising and seller-services income, since ads grew 31%, to keep improving margins without cutting growth.
- Expect Flipkart to hold its cost discipline and trim unit-economics drags such as returns and delivery costs, while still investing enough to keep revenue growth near FY26's 18%.
- Amazon India and Reliance Retail may respond with sharper pricing or faster delivery in categories where Flipkart is trying to cut subsidies.
- Flipkart's sellers are likely to face higher promotion and ad costs, and some may shift spend to rival platforms or their own channels.
- Flipkart's parent and investors will more likely than not keep presenting the narrowing loss as progress, though they are unlikely to claim profitability yet.